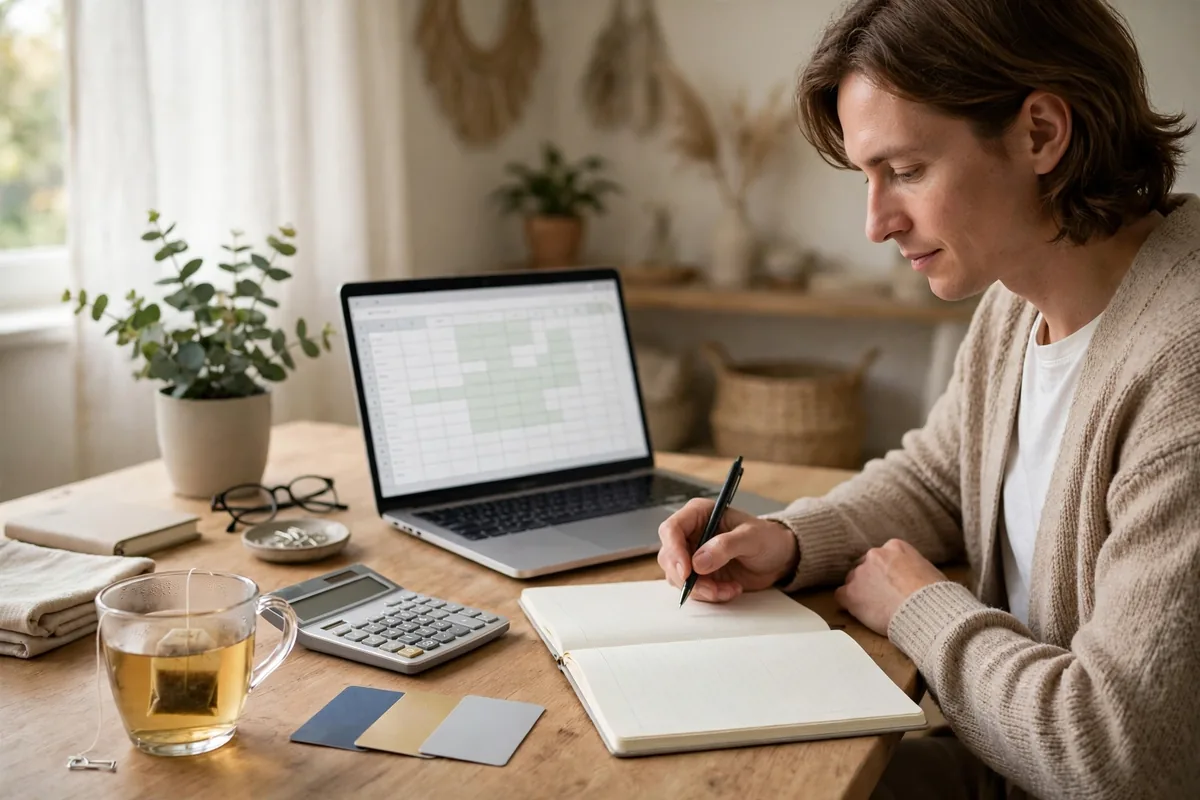
A monthly budget is not about depriving yourself or tracking every penny forever. It is simply a plan that tells your money where to go before the month begins, instead of leaving you wondering where it went at the end. If you have never budgeted before, the good news is that a simple system you actually follow beats a complicated one you abandon by the second week. This guide shows beginners how to build a monthly budget that works in real life.
Step One: Know What Really Comes In
Start with your actual take-home pay, not your salary before tax. If your income varies from month to month, base the budget on your lowest typical month and treat anything above it as a bonus to save or use for one-off goals. Add any regular extra income, such as benefits, a side job or rental income, but only count what reliably arrives.
Write the figure down. Many people are surprised at this first step alone, because the gap between what we think we earn and what actually lands in the bank explains a lot of end-of-month stress.
Step Two: List What Really Goes Out
Go through the last two or three months of bank statements and list everything. Group spending into essentials (rent or mortgage, council tax, utilities, food, transport, insurance, minimum debt payments) and flexible spending (eating out, subscriptions, clothes, entertainment). Be honest about the small recurring leaks: the streaming services you barely watch and the daily coffee habit are classic examples.
Motoring costs deserve their own line because they are easy to underestimate. Fuel and insurance are obvious, but servicing, repairs and the annual MOT arrive in lumps. Our breakdown of the economics of keeping a car in the UK shows why spreading these costs monthly is far easier than meeting them all at once.
Step Three: Give Every Pound a Job
Now divide your income deliberately. A popular starting point is the 50/30/20 rule of thumb: roughly half of take-home pay for needs, a third for wants, and a fifth for savings and extra debt payments. Treat it as a compass, not a law. If rent in your area eats more than half your income, adjust the other slices rather than giving up entirely.
The key is that savings become a planned line in the budget, like a bill you pay yourself first, instead of whatever happens to be left over. Even a small fixed amount builds the habit, and the habit matters more than the amount at the start.
Plan for Irregular and Motoring Costs
Most budgets fail because of expenses that are predictable but not monthly: car insurance renewals, birthdays, Christmas, boiler servicing, holidays. List them, estimate the yearly total for each, divide by twelve and set that amount aside monthly in a separate pot or account. When the bill arrives, it is already paid for.
Cars are the biggest culprit. A surprise repair bill can wreck an otherwise good month, which is why so many drivers end up looking at ways of paying for unexpected car repairs after the event. A monthly car pot covering servicing and likely repairs removes most of that pressure. It also helps to understand why vehicle maintenance costs are rising so your pot keeps pace with real prices. If you are financing the car itself, make sure you understand the full commitment described in our guide to car finance in the UK before signing anything.
Build a Starter Emergency Fund
Before investing or overpaying debts aggressively, build a small emergency cushion. An initial target of a few hundred pounds handles most everyday shocks: a broken washing machine, a lost phone, an urgent repair. After that, work towards one month of essential spending, then three. Keep the fund in an easy-access savings account, separate from your everyday money so it is not spent by accident.
An emergency fund is what turns a crisis into an inconvenience. Without one, every surprise goes on a credit card and the budget never gets a chance to work.
Common Budgeting Mistakes Beginners Make
The most common mistake is building a budget around the month you wish you had rather than the one you actually live. If eating out with friends is part of your real life, give it a realistic allowance instead of banning it and failing by the second weekend. Another classic error is forgetting annual and quarterly bills, which then ambush the budget several times a year. A third is making the budget so detailed that updating it feels like a second job; ten to fifteen categories is plenty for most households.
Finally, do not treat one bad month as proof that budgeting does not work. Everyone overspends sometimes. The budget’s job is to show you what happened and help you correct course, not to deliver a perfect score every month.
Review, Adjust and Keep It Simple
Sit down once a month, ideally just after payday, and compare the plan with what actually happened. Where did you overspend? Was it a one-off, or is the budget itself unrealistic? Adjust the categories rather than abandoning the system. A budget that bends survives; a rigid one snaps.
Keep the tools simple: a notes app, a spreadsheet or a budgeting app all work. What matters is the monthly habit. And when big purchases come up, budget thinking helps there too. Knowing how the second-hand car market works and how platforms described in our guide to AutoTrader UK shape prices puts you in a far stronger position than buying in a rush.
Your First Month, Step by Step
If the whole process feels daunting, shrink it to a single week of action. On day one, write down your take-home pay and list your essential bills with their dates. On day two, go through last month’s statements and sort your spending into the groups described above. On day three, set your savings amount and your monthly pots for irregular costs, and set up the transfers for payday so they happen automatically. Then stop tinkering. Live with the budget for the rest of the month, note where it pinches, and fix the pinch points at your first monthly review. Automation does the heavy lifting: when savings and bill money leave your account the day after payday, willpower stops being part of the equation.
Start with this month’s real numbers, give every pound a job, plan for the lumpy costs, and review as you go. That is all a monthly budget needs to be: a plan you can actually live with.